


 20.10.2026
 Read Time:
20 minutes


The road ahead for central banks
Alessia Berardi
Head of Global Macroeconomics & Emerging Markets Strategy, Amundi Investment Institute
KEY TAKEAWAYS
In a low-trust world that is becoming increasingly predatory, investors should expect supply shocks to become a new norm and the distribution of economic gains to stay uneven. Another result of the global order fragmenting is the rise of fiercer competition between countries. However, this competition is no longer limited to trade, tech, industrial leadership or energy security; it is instead being shaped by a relentless search for capital at the public and private level.
Competition does not necessarily imply weak growth. In some regions, the race for innovation and the pursuit of strategic autonomy are actually supporting, if not boosting, economic activity. What makes the picture more fragile is the concentration of that economic performance: growth is increasingly resting on a narrow base.
Ultimately, countries are all investing in the same sectors, and growth policies are shifting away from consumption and labour towards investment and capital. In this new environment, the economic benefits will be less and less evenly distributed.
At the same time, waiting for innovation to deliver price stability or for demographic trends to suppress demand is not a viable short-term strategy. Inflationary pressure is likely to persist. On the demand side, the investment surge into strategic autonomy, high energy needs and competition for critical resources all collide with scarcity. For critical minerals, supply is constrained by refining and processing, which sits in just a few hands. On the cost side, we are moving into a “toll world”: as chokepoints and waterways become contested, the friction of moving goods rises, and those costs feed straight through to prices. Finally, climate events will materially affect food security and food inflation.
Whether governments are pursuing supremacy, adaptation or survival, this evolving environment requires policy adaptation. For policymakers, the surge in economic and financial warfare means that monetary and fiscal policy increasingly need to be considered together. As a result, fiscal policy is acquiring more importance, while monetary policy might increasingly be left to complement fiscal policy rather than anchor the entire macroeconomic framework on its own, with important repercussions on the market.
The problem is that fiscal policy’s broader ambitions collide with the almost global absence of fiscal room. Overall, subdued growth is generating insufficient revenues to revert high debt ratios. In many countries, binding fiscal rules also remain. High debt, high debt-service costs and high rates form a toxic combination – and we have recently seen an effort by the US Treasury to keep interest rates low.
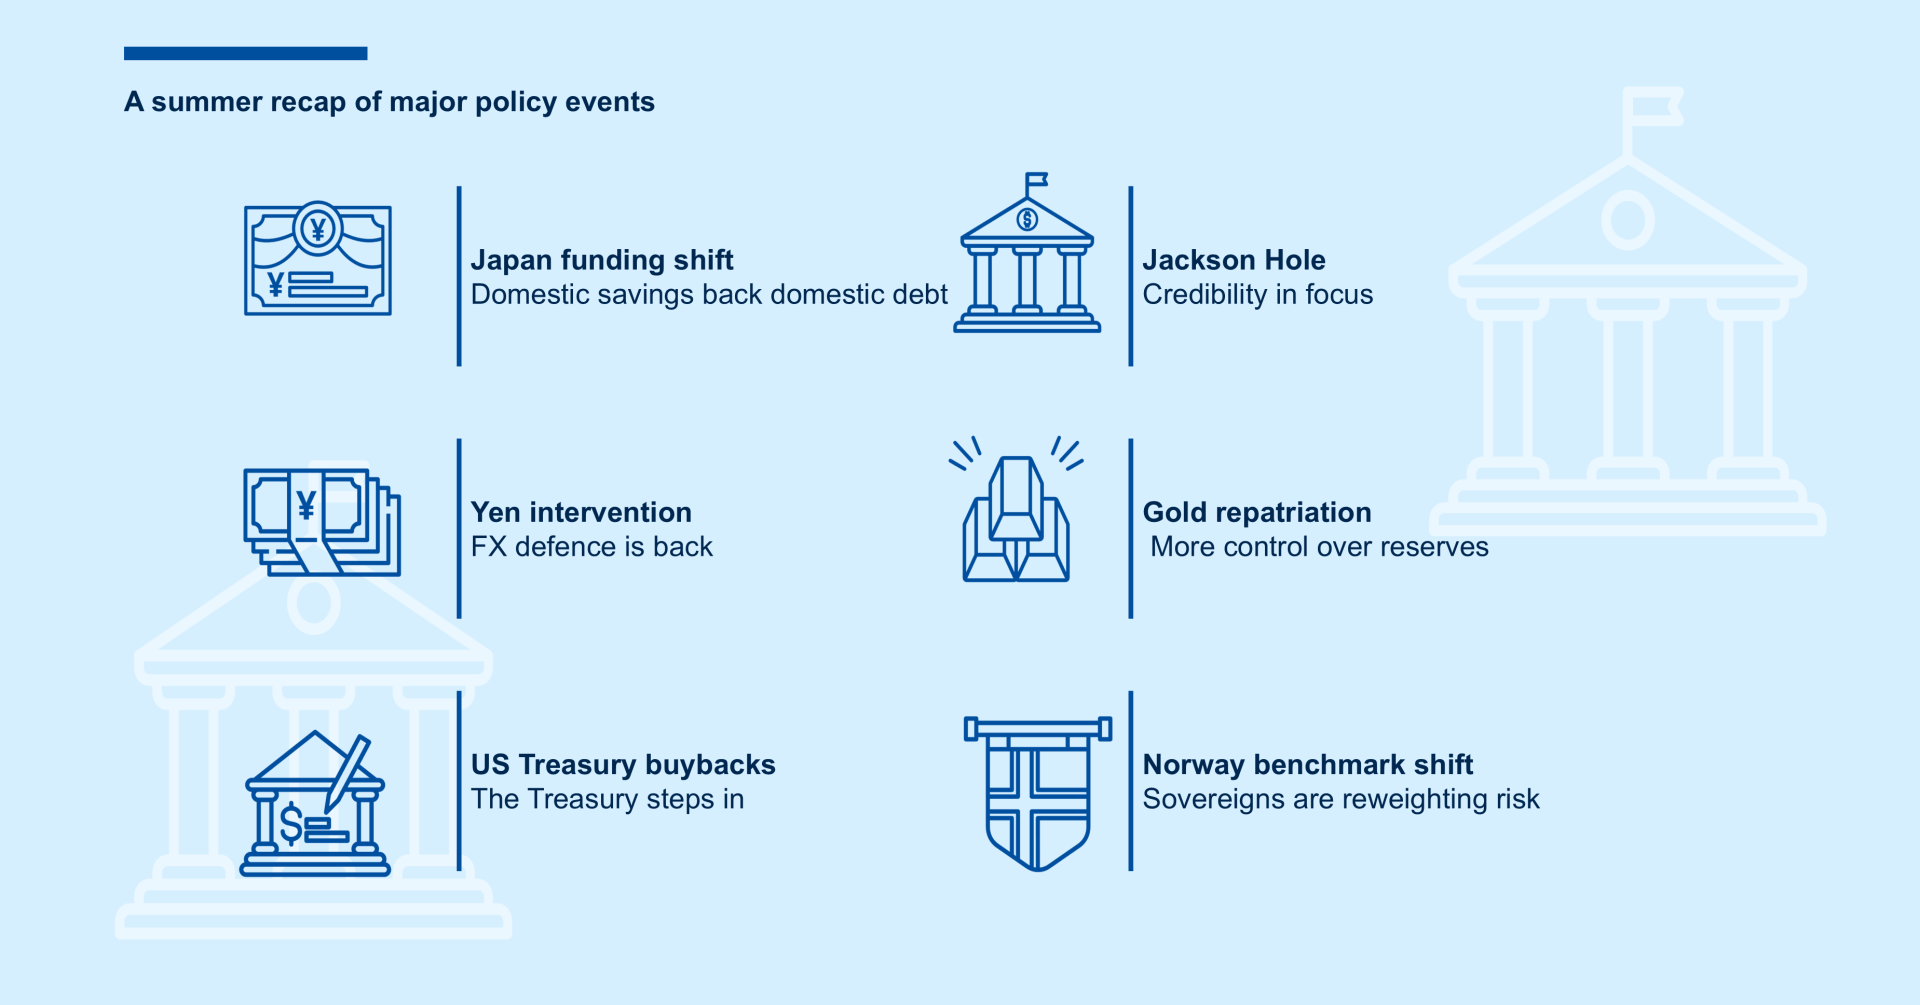
With that in mind, it’s worth revisiting the events of the summer because they may appear unrelated, but they are not.
Domestic investors invited to fund domestic debt. In July, Japan’s Finance Ministry encouraged pension funds and households to invest more heavily in domestic assets; it also floated the idea of putting government bonds inside the tax-free NISA wrapper and began designing new retail JGB products. Japan wants its own savings to finance its own debt, just as the BoJ is stepping back from the market and catching up with more entrenched inflation.
Unconventional policy tools being used at a time when the financial structure of sovereign bond markets appears more fragile precisely because of the fiscal-financial stability nexus.
After the yen weakened sharply, the BoJ carried out its largest monthly intervention on record. Washington joined in, saying it would not hesitate to do so again. The details matter more than the headline: the US Treasury sold euros, not Treasuries, to fund its yen purchases. Tokyo signalled it could use the Fed’s FIMA repo facility in future, allowing it to borrow dollars against Treasuries rather than sell them. In effect, the intervention protected the US Treasury market as much as it supported the yen.
The US Treasury then moved directly to the long end of the curve. It announced that it would triple the size of its long-dated buyback operation from $2bn to $6bn.
Policy credibility in focus. With fiscal sustainability under review and yields swinging, monetary policy must remain credible and unambiguously committed to price stability. Warsh had little choice but to sound hawkish at Jackson Hole and to deliver a rate hike. In the US, inflation remains elevated and core pressures are unlikely to ease quickly. Risks remain tilted to the upside, from Middle East energy shocks to higher food and commodity prices. The Fed’s credibility matters, and a mild hiking cycle could actually keep yields lower, at least in the short term. A sizable hiking cycle is still not our base case: we remain closer to the dots than to the market.
Crisis preparedness.
The Dutch Central Bank shifted 86 tonnes of gold out of NY and Ottawa between March and August, disclosing it only once the operation was complete. London has now 32.1% of the country’s gold stock, up from 18.1%. Most of the transfer was executed by selling in NY and buying in London rather than shipping bars. The stated reason was tradability and crisis preparedness. The unstated reason was more direct control.
Norway went even further. Norges Bank Investment Management is proposing to the Finance Ministry to cut the government share of its bond benchmark from 70% to 50%. It also wants to switch from GDP weighting to market-value weighting, reflecting the reality that DM debt has outgrown output. Under such a framework, Treasuries would fall and Japanese bonds would rise. A decision is expected in 2027.
These are not independent stories. The old model of recycling global savings into US bonds is fading. Creditors are going home for diversifying. The debtor is buying its own paper. The term premium has turned into a political variable and is structurally higher.
The USD bear case faces a monetary-policy test
Federico CESARINI
Head of DM Equity, FX and Digital Assets, Amundi Investment Institute
Key Takeaways
We entered 2026 expecting expensive valuations and Fed easing, alongside an administration increasingly focused on limiting the cost of financing a deteriorating fiscal position. Together, these conditions were expected to gradually normalise the USD.
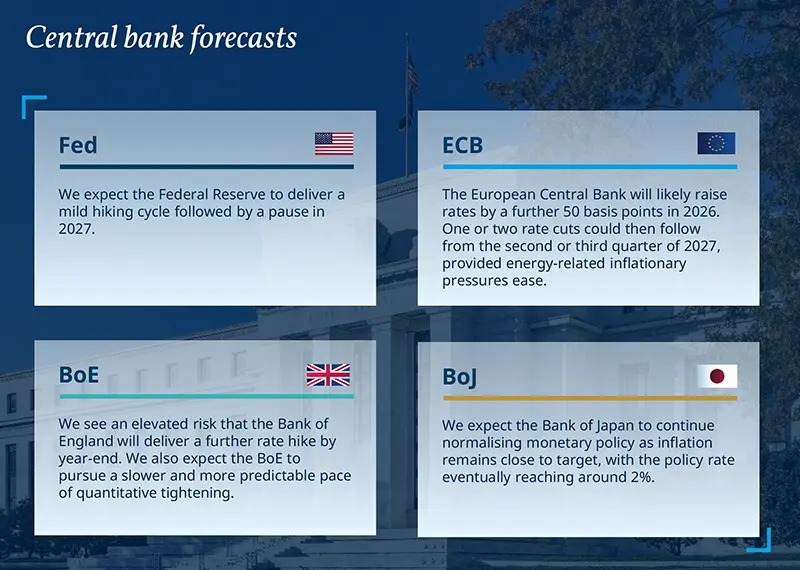
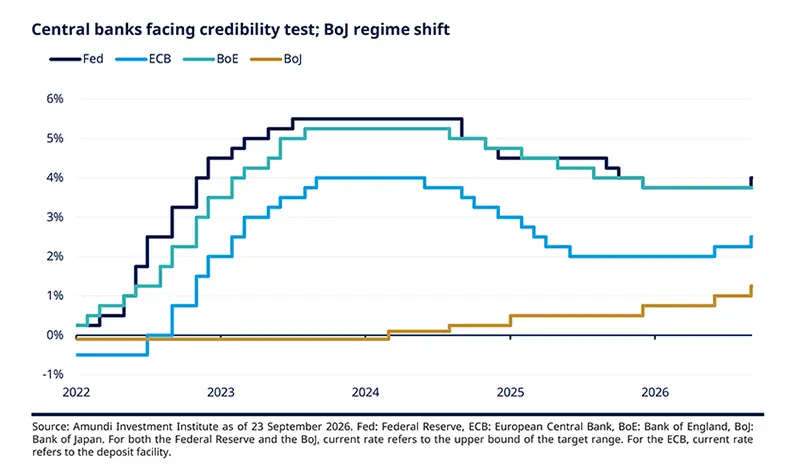
The September Fed hike challenges the timing of that view. As the curve flattens and uncertainty around the terminal rate of this cycle rises, the window for broad-based USD weakness appears to be closing. In the near term, carry and relative value matter more than outright USD weakness. A renewed broad decline in the dollar would likely require inflation, and ultimately the Fed, to turn first. As we expect the Fed to deliver less than the market currently prices, we think any renewed dollar strength should be limited, and we would ultimately expect USD weakness to resume further down the road.
The key dividing line is the Fed, and this goes beyond the USD
Market expectations have moved rapidly from cuts towards hikes, while the change in Fed leadership has introduced substantially more uncertainty around its reaction function. Warsh’s communication since Jackson Hole has emphasised the Fed’s commitment to price stability and the need to bring PCE inflation convincingly back towards 2%. History points to an uncomfortable tail risk: when hiking cycles have started with inflation around current levels, around 150–200bp of tightening during the first year has not been unusual. This is the central risk confronting any bearish USD view today. Given Warsh’s communication, further progress on inflation is increasingly necessary to prevent markets from pricing a similar path, which would be particularly supportive for the USD.
So far, the repricing has been surprisingly benign for markets. Rates volatility remains low, helping explain why higher expected policy rates have not generated a meaningful deterioration in risk sentiment or a rise in FX volatility. But renewed uncertainty about where the Fed ultimately intends to take rates (and the price-discovery process around that terminal rate) could change this quickly. The principal risk is therefore no longer simply one or two additional hikes, but evidence that Warsh is prepared to pursue a genuine tightening cycle. If inflation fails to improve, this risk is likely to remain firmly priced in.
A September hike followed by further tightening therefore closes, for now, the window for broad-based USD weakness. The relevant question has shifted from whether the adjustment continues to what would be required for that window to reopen. Given the challenging high energy / high rates mix globally, and the worsening political backdrop in Europe (in 2025 the EUR benefitted from hopes of fiscal expansion, greater European integration and a stronger policy response, but the upcoming electoral cycle raises the risk of a delay of those trends), any material weakness remains a function of the USD leg instead.
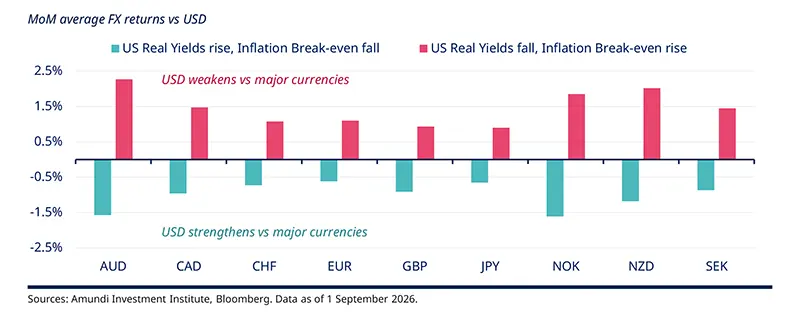
The best cyclical conditions for the USD occur when US real yields rise and compress inflation expectation. The worst occur when the Fed suppresses real yields and lets inflation run.
Our USD view has little to deal with de-dollarisation. The USD’s role remains intact, but the medium-term question around its value has not disappeared
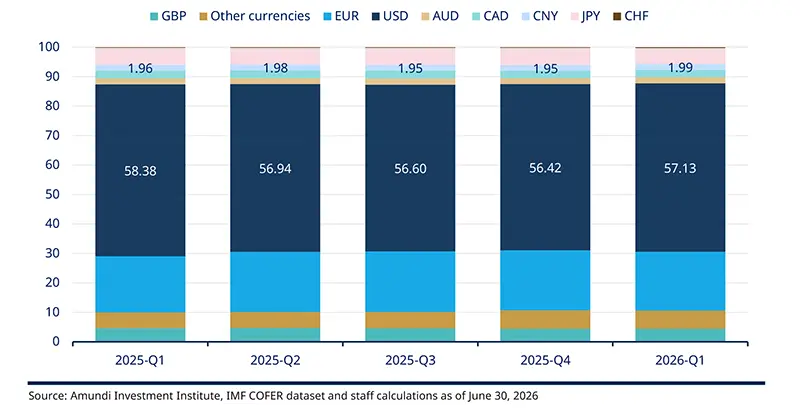
Our structural question marks over the USD should not be confused with a de-dollarisation call. The latest available IMF COFER data provide little evidence of an abrupt shift away from the greenback (see chart below). In Q1 2026, the USD share of allocated global FX reserves increased to 57.13%, from 56.42% in Q4 2025. While more than half of the increase reflects exchange-rate valuation effects rather than active reserve allocation, the underlying message remains one of remarkable stability in the international role of the currency. Central banks are diversifying, but the clearest marginal alternative remains gold rather than another fiat currency. There is little evidence that reserve managers are replacing the dollar with the euro, yen or renminbi at a pace capable of materially challenging the existing reserve architecture. This is consistent also with the latest BIS Triennial Central Bank Survey.
Currency composition of foreign exchange reserves (%)
In our view, the medium-term challenge remains the interaction between US fiscal sustainability, the price of capital and the opportunity set outside US assets. The US faces a rapidly rising interest burden, exceptionally large refinancing needs and a stock of government debt that needs to be continuously absorbed. The relevant risk is whether fiscal arithmetic eventually produces pressure for some form of financial repression (through inflation, regulation, captive balance sheets or other mechanisms) that eventually limits the real financing cost of the government. In such a regime, the currency can become both a shock absorber and an equilibrating mechanism. A weaker USD raises prospective returns on US assets for foreign investors by reducing their entry price in home-currency terms and could eventually become part of the adjustment required to maintain global capital flows towards the US.
This is why the Fed remains the critical variable even after the September hike. If Warsh is orthodox and resilient nominal growth keeps policy restrictive, cyclical tailwinds will likely support the USD, despite the growing medium-term headwinds. But if, on the other hand, policy attempts to reconcile above-target inflation, resilient nominal growth and increasingly difficult public-debt arithmetic by suppressing real financing costs relative to what a conventional Taylor-rule framework would imply, the structural adjustment in the USD can reopen.
Carry remains attractive, but choosing the funding currency matters more than ever
Global growth remains relatively resilient, commodity prices are elevated and cross-asset volatility, particularly rates and FX, has remained contained. These are normally supportive conditions for carry.
Now, if September marks the beginning of a genuine Fed hiking cycle and markets are underestimating its extent, there is ultimately limited diversification that carry can provide against a broad volatility shock. If September does not mark the beginning of a genuine Fed hiking cycle and if the market is not surprised by this extent, we continue to see valid reasons for the carry strategy to perform. AUD and NOK remain our preferred G10 high-beta expressions, alongside selected high-yielding EM currencies where valuations and carry remain attractive. The funding mix is, though, as important as the carry itself. The rising risks suggest to prefer low-yielding European currencies (SEK, EUR, CHF) as funders, rather than the USD or the JPY.
The JPY deserves particular caution
The BoJ has become more credible in signalling further normalisation, and higher JGB yields are improving the relative attractiveness of domestic fixed income. But the tightening cycle is still likely to be shallow compared with other central banks, limiting the case for treating the yen as a conventional high-conviction long. Rather, the JPY increasingly looks like the least unattractive among the traditional funding currencies. Capital repatriation, improving domestic yields and the authorities’ willingness to resist excessive depreciation leave the balance of risks skewed towards gradual appreciation.
A disorderly JPY appreciation, typically associated with a volatility spike and weaker global growth and BoJ tightening substantially beyond what markets price, would be a key risk to carry through. But our base case remains a more gradual adjustment. And if that adjustment broadens into Asian FX, where currencies remain historically cheap despite strong external balances, it could eventually provide another channel through which the structural USD adjustment re-emerges.
IMPORTANT INFORMATION
The MSCI information may only be used for your internal use, may not be reproduced or disseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to compiling, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranty of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages. (www.mscibarra.com).
The Global Industry Classification Standard (GICS) SM was developed by and is the exclusive property and a service mark of Standard & Poor's and MSCI. Neither Standard & Poor's, MSCI nor any other party involved in making or compiling any GICS classifications makes any express or implied warranties or representations with respect to such standard or classification (or the results to be obtained by the use thereof), and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability or fitness for a particular purpose with respect to any of such standard or classification. Without limiting any of the forgoing, in no event shall Standard & Poor's, MSCI, any of their affiliates or any third party involved in making or compiling any GICS classification have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages.
This document is solely for informational purposes. This document does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation of any security or any other product or service. Any securities, products, or services referenced may not be registered for sale with the relevant authority in your jurisdiction and may not be regulated or supervised by any governmental or similar authority in your jurisdiction. The information contained in this document must not be altered or presented in a way that could give rise to misunderstanding or misrepresentation. Any use, reproduction, or distribution of the document’s content without full and proper reference to the original source is prohibited. Any information contained in this document may not be used as a basis for or a component of any financial instruments or products or indices. Furthermore, nothing in this document is intended to provide tax, legal, or investment advice. Unless otherwise stated, all information contained in this document is from Amundi Asset Management S.A.S. and is as of 29 September 2026. Diversification does not guarantee a profit or protect against a loss. This document is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. Historical data and analysis should not be taken as an indication or guarantee of any future performance analysis, forecast or prediction. The views expressed regarding market and economic trends are those of the author and not necessarily Amundi Asset Management S.A.S. or Amundi-Acba Asset Management CJSC and are subject to change at any time based on market and other conditions, and there can be no assurance that countries, markets or sectors will perform as expected. These views should not be relied upon as investment advice, a security recommendation, or as an indication of trading for any Amundi or Amundi-Acba product. Investment involves risks, including market, political, liquidity and currency risks. Furthermore, in no event shall Amundi or Amundi-Acba have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages due to its use.
Date of first use: 29 September 2026.
"AMUNDI-ACBA ASSET MANAGEMENT" CJSC is a legal entity registered in Armenia, who, based on the Investment fund management license number 0002, provided by the Central Bank of Armenia, carries out mandatory pension fund management activities in Armenia. The registered office is located 10 Vazgen Sargsyan street, Premises 100-101, Yerevan, Armenia.
For more information about Amundi-Acba you can visit www.amundi-acba.am or call 011-310-000.

